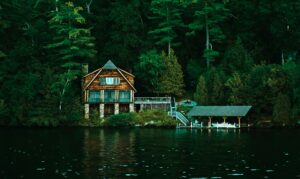
Representative stock image. Photo by Bjørn-Magnus Kristiansen on Unsplash.
Which dock comes with the cabin? Who maintains the private road? Will anyone visit when the property is closed for the season? These are insurance questions worth raising while you still have time to investigate the answers.
A lakeshore purchase brings together the building, waterfront equipment, access arrangements and your intended use. A listing sheet rarely explains all four. Use this checklist to organize an insurance review alongside your inspections and purchase process, rather than leaving it until the lender requests proof of coverage.
Before the offer describe how you will use the cabin
Tell your insurance agent whether the property will be a year-round residence, a weekend retreat, a summer-only cabin or a place you may rent. Explain who will stay there, how long it may go unattended, whether heat will remain on and who can respond to a problem.
Farmers' vacation-home guidance explains that second homes present different risks when problems go unnoticed and that rental activity may require different coverage. Describe your intended use rather than adopting the seller's description of the property.
Your first checklist should include:
- Expected months of use and the longest likely absence.
- Whether plumbing will remain active or be professionally winterized.
- Any planned guest stays, paid rentals or shared ownership.
- Renovation work expected before you first occupy the cabin.
Discuss those facts early. If insurance availability or unresolved conditions could affect your willingness to buy, ask your real estate professional or attorney how to address that within the purchase process.
List the waterfront property separately from the cabin
Walk the lot and create an itemized inventory: dock sections, boat lift, lakeside stairs, railings, sauna, boathouse, storage shed, retaining features and detached guest space. Ask which items belong to the seller, which are shared and which are included in the transaction. Have ownership and access rights verified through the appropriate purchase documents and professionals.
For each item you intend to own, ask the agent where it would be addressed in the proposed insurance. What causes of damage are covered? What limits, exclusions or separate coverage apply? Do removal, off-season storage or a different location change the answer?
The Minnesota DNR's dock and water-access guidance describes requirements for waterfront access structures. Treat an existing dock as something to verify, not proof that its layout is authorized or that it is insured. Collect available permits and installation records, and ask the appropriate authority about unresolved questions.
During inspections verify access and protective systems
Drive the actual access route and ask about conditions outside the showing season. Who plows? Who maintains a shared lane or bridge? Are there gates, steep sections, turnaround limitations or periods when the road is difficult to use? Ask the insurer what access and fire-protection information it needs, and verify details rather than estimating from a map.
The University of Minnesota Extension's shoreland purchasing guidance recommends checking local zoning before buying and considering septic, utilities and emergency-vehicle access. Keep those investigations alongside the insurance review; a policy does not replace a property inspection or resolve land-use questions.
Have your inspector or appropriate specialist identify the heating system, electrical updates, water shutoff and any fireplace or wood stove. Request available service records. Confirm whether smoke alarms, leak sensors, temperature monitoring or security devices actually work, who receives alerts and what happens during a power or internet outage. Ask about insurer requirements without assuming a device guarantees eligibility or a discount.
Resolve open insurance questions before closing
Send the agent inspection findings, building details and the waterfront inventory. Ask for a proposal based on verified information, including any required repairs or inspections. Review the dwelling estimate, detached-structure treatment, belongings, liability, deductibles and the specific exclusions most relevant to this property.
Discuss flood protection separately. FEMA's flood-insurance guidance states that NFIP coverage generally has a 30-day waiting period, with exceptions including certain mortgage transactions. Ask which effective-date rules apply to your purchase rather than assuming every closing automatically eliminates a wait.
Do not treat a preliminary price indication as confirmation that coverage is in force. Ask what remains outstanding, when coverage can begin and what documents the lender needs. If the closing date changes, notify the agent so the effective date can be checked again.
Make the final walkthrough an insurance handoff
Before taking possession, confirm that the agreed waterfront items remain, required repairs have been documented and your contact or caretaker arrangements are ready. Keep the inventory, inspection reports, permits, insurance confirmation and emergency contacts together. Calendar a review if you later change occupancy, start renting or add a waterfront structure.
For help organizing the insurance side of a Minnesota lakeshore purchase, call David Olson at Intrinsic Insurance at 952-314-9446. Share the listing and your intended use early, then update the conversation as inspections and closing details develop.
 One of the things that sets Intrinsic Insurance apart is our commitment to our customers. We believe that insurance should be easy to understand and easy to use, and we strive to make the process as smooth and stress-free as possible. Our agents take the time to get to know our customers and their unique needs, so we can provide personalized coverage that meets their specific requirements. Over time, we’ve earned a reputation for exceptional customer service and expertise in the insurance industry, real estate, and construction. We’re proud to have a team of experienced agents who are dedicated to providing our customers with the highest level of service and support. Our agents are knowledgeable, friendly, and always available to answer questions or help our customers file a claim.