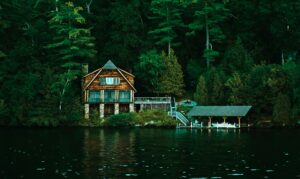
Representative stock image. Photo by Pete Alexopoulos on Unsplash.
A wet floor at the cabin tells you where water ended up. It may tell you very little about where it started. At a lakeshore property, water can arrive from the lake, a road above the lot, a backed-up drain or soil pressed against the foundation. Those different routes can lead to different insurance questions, even during the same storm.
Before the next heavy rain or spring thaw, walk the property with those routes in mind. A useful coverage conversation starts with the cabin's actual setting, not simply whether someone calls the damage a “flood.”
Inspect the land above the cabin
Stand near the road or driveway and look toward the building. Does the drive slope toward a garage? Is there a low spot beside a walkout door? Where would water go if a roadside ditch or culvert could not carry it away? Then walk around to the lake side and identify the lowest door, window well and crawlspace opening.
Make a simple sketch showing those points, the sump discharge, downspouts and shoreline. You are mapping questions, not diagnosing the property yourself. A drainage professional can evaluate problem areas; check with the appropriate local authority before changing drainage or shoreland grading.
Ask about flood insurance even if the cabin has never had water damage. Standard homeowners insurance does not provide flood coverage, as the Minnesota Department of Commerce explains. The lake does not have to be the starting point for an outdoor-water concern.
Separate lake overflow from water crossing the lot
A rising lake and runoff moving downhill from another part of the property can both raise flood-insurance questions. Under the NFIP definition, a flood generally involves temporary inundation of normally dry land affecting at least two acres or two properties, including the insured property, from specified causes such as inland-water overflow or unusual, rapid surface-water accumulation. Review the NFIP's official flood definition, rather than assuming that any puddle at one cabin qualifies.
For your review, describe realistic pathways: lake water reaching the lower doorway, runoff crossing the driveway into the garage, or snowmelt pooling around the cabin. Ask how each proposed policy defines flood and which buildings and contents would be insured. Private flood forms can differ from NFIP coverage, so compare the wording of the actual options presented.
Treat backup and foundation seepage as separate questions
A sump-pump endorsement should not be treated as an all-purpose solution for water coming into a lake cottage. Backup coverage may be available by endorsement, but its terms and treatment of a simultaneous flood vary. Minnesota Commerce also identifies water seeping through basement walls or floors among typical homeowners water exclusions. Its sewer-backup guidance is a useful starting point for reviewing these distinctions.
Tell your agent whether the cabin uses municipal sewer or a septic system. Ask which drains, sumps and related equipment the endorsement addresses, whether power interruption matters, and what limit and deductible apply. Do not assume that a sewage-related loss, failed pump and water through a foundation joint receive the same treatment.
There is an important NFIP nuance: flood-caused backup, sump overflow or seepage may be covered when a qualifying flood is the proximate cause, subject to the policy. That is different from ordinary groundwater seepage or a clogged drain. FEMA's NFIP Claims Manual explains this causation requirement. Water entering through a wall does not, by itself, settle the coverage question.
Build a lakeshore water review packet
Before calling, gather:
- Photos looking from the road to the cabin and from the cabin to the lake.
- A sketch of low openings, drainage routes, the sump and its discharge location.
- Your cabin policy, water endorsements and any separate flood policy.
- Details of prior dampness, pump problems or water events, including dates and repairs.
- A list of lower-level belongings and equipment you would want discussed individually.
Ask the agent to walk through each water route and identify the applicable coverage, exclusions, limits and unresolved questions. If water damage occurs, document what you can safely observe without guessing at the cause or entering an unsafe area.
For help organizing a lakeshore-specific coverage review, call David Olson at Intrinsic Insurance, 952-314-9446. Bring the sketch and policies so the conversation can focus on your cabin's water pathways and the terms that apply.
 One of the things that sets Intrinsic Insurance apart is our commitment to our customers. We believe that insurance should be easy to understand and easy to use, and we strive to make the process as smooth and stress-free as possible. Our agents take the time to get to know our customers and their unique needs, so we can provide personalized coverage that meets their specific requirements. Over time, we’ve earned a reputation for exceptional customer service and expertise in the insurance industry, real estate, and construction. We’re proud to have a team of experienced agents who are dedicated to providing our customers with the highest level of service and support. Our agents are knowledgeable, friendly, and always available to answer questions or help our customers file a claim.